Marli Voss Hartmann da Silva
University Professor – UNIARP
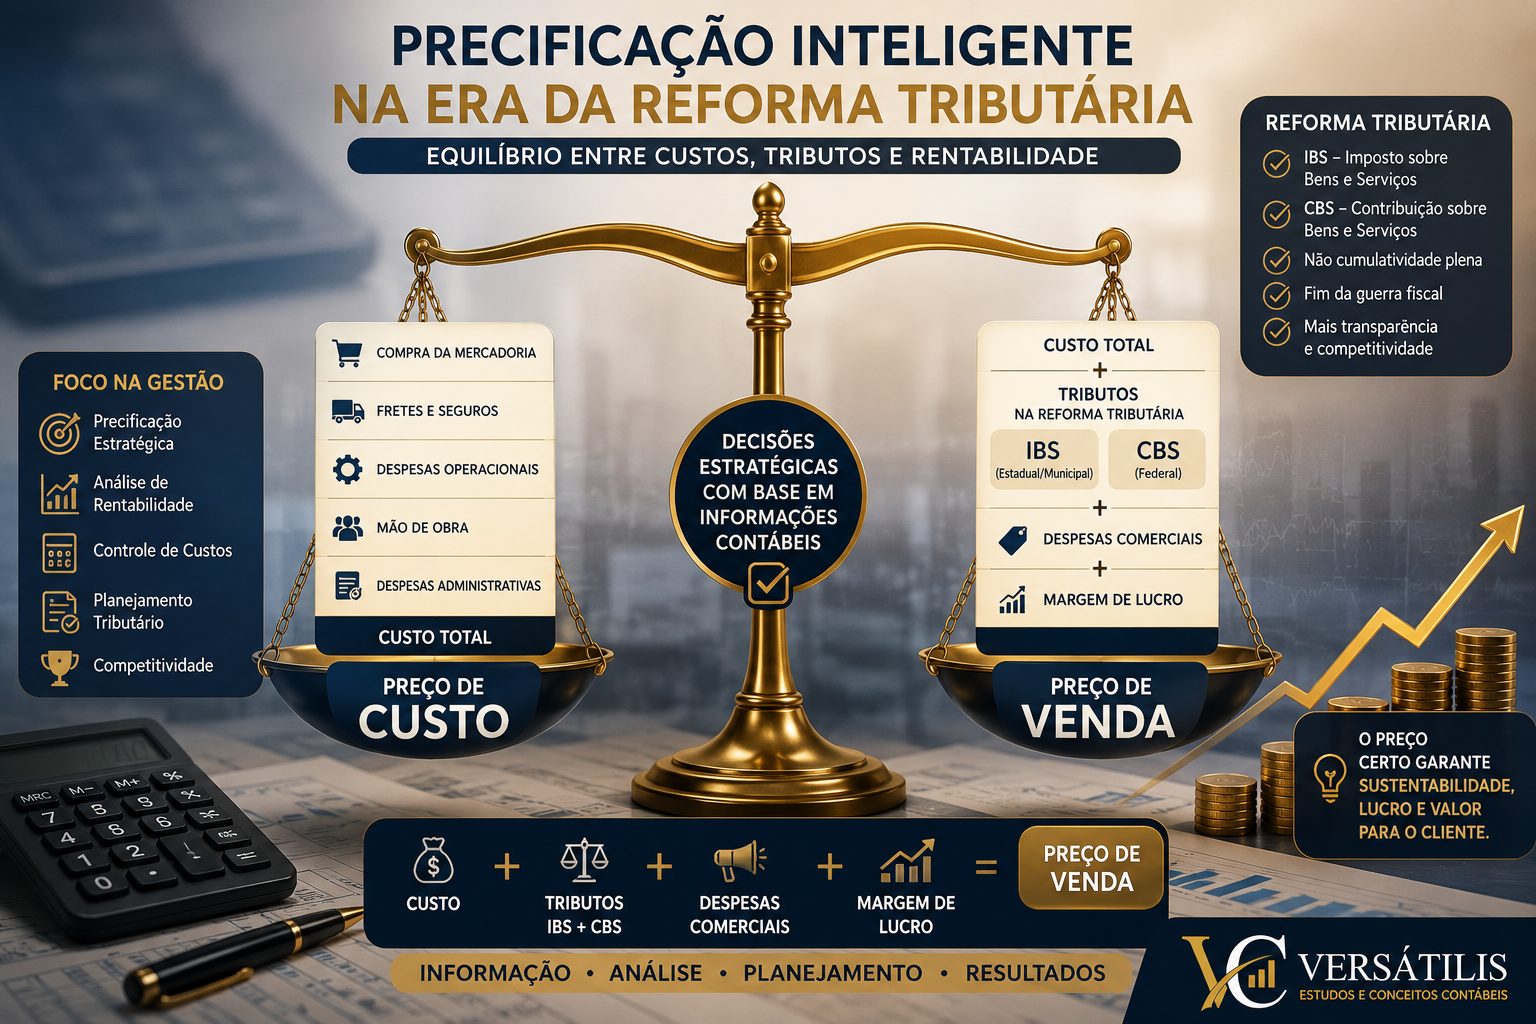
The formation of the sale price is one of the main business management tools. With the regulation of the Reforma Tributária, companies opting for Simples Nacional need to review their pricing models to maintain competitiveness and economic efficiency.
Theoretical Framework
Complementary Law No. 123/2006 established Simples Nacional as a simplified regime. Complementary Law No. 214/2025 regulated Constitutional Amendment No. 132/2023 and created CBS, IBS, and the Selective Tax, promoting structural changes in Brazilian taxation.
Comparison of Legislations
Case Studies
Case Study 1 - Retail Trade
Company: Comercial Alfa Ltda.
Tax regime: Simples Nacional
Assumptions: cost R$ 138.00; commission 4%; profit 25%; DAS 8.5%; reform scenario 11.0%.
|
Indicator |
Complementary Law 123/2006 |
Complementary Law 214/2025 |
|
Cost |
BRL 138.00 |
BRL 138.00 |
|
Taxes |
8.5% |
11.0% |
|
Sale Price |
R$ 220.80 |
R$ 230.00 |
Discussion: keeping the same profit margin, the increase in tax burden in the simulation raises the selling price. In practice, the analysis must consider IBS/CBS credits, customer profile, and specific rules of the legislation.
Case Study 2 - Industry
Company: Indústria Beta Ltda.
Tax regime: Simples Nacional
Assumptions: cost R$ 185.00; commission 4%; profit 25%; DAS 9.5%; reform scenario 12.0%.
|
Indicator |
Complementary Law 123/2006 |
Complementary Law 214/2025 |
|
Cost |
R$ 185.00 |
R$ 185.00 |
|
Taxes |
9.5% |
12.0% |
|
Sale Price |
R$ 300.81 |
R$ 313.56 |
Discussion: keeping the same profit margin, the increase in tax burden in the simulation raises the selling price. In practice, the analysis must consider IBS/CBS credits, customer profile, and specific rules of the legislation.
Case Study 3 - Service Provision
Company: Gama Services Ltd.
Tax regime: Simples Nacional
Assumptions: cost R$ 210.00; commission 4%; profit 25%; DAS 11.5%; reform scenario 13.5%.
|
Indicator |
Complementary Law 123/2006 |
Complementary Law 214/2025 |
|
Cost |
BRL 210.00 |
BRL 210.00 |
|
Taxes |
11.5% |
13.5% |
|
Sale Price |
R$ 352.94 |
R$ 365.22 |
Discussion: keeping the same profit margin, the increase in tax burden in the simulation raises the selling price. In practice, the analysis must consider IBS/CBS credits, customer profile, and specific rules of the legislation.
Conclusion
The results demonstrate the importance of tax planning in setting the sale price. It is recommended to expand this study using real company data and different scenarios by Simples Nacional bracket.
The Reforma Tributária expands the importance of tax planning and strengthens the role of the accountant as a strategic agent in pricing and business decision-making.
References
BRAZIL. Constitutional Amendment No. 132/2023. BRAZIL. Complementary Law No. 123/2006. BRAZIL. Complementary Law No. 214/2025. IUDÍCIBUS, Sérgio de. Accounting Theory. MARTINS, Eliseu. Cost Accounting. PADOVEZE, Clóvis Luís. Strategic Controllership.